
With Anthropic’s S-1 now filed with the SEC, over 5,000 employees are about to become extremely wealthy. We’re talking about the median employee making $3 million to $10 million within three years, and likely at least a thousand people making well into eight figures or more.
The numbers behind it are astounding. The filing shows $16.3 billion in revenue for the first half of 2026, up from about $1.2 billion a year earlier. Since Opus 5.5 launched on September 22, 2026, token usage for Claude has grown roughly 3.6X. The company has over $130 billion in cash and investments, is already generating an operating profit, and is about to raise tens of billions more in its IPO. Pretty darn impressive.
For employees, making that much money in so little time is like winning the lottery. You got lucky getting on the right ship. With proper financial management, you and your children could be set for life.
Profiting From AI As An Outsider
For the rest of us commoners, luck is harder to come by. We can buy real estate in the cities where AI companies are headquartered and hope the wealth trickles into home prices and rents. We can invest in private and public venture capitaland hope the general partners picked the right companies. But even then, our exposure likely won’t come close to that of early AI employees who got equity as part of their paycheck.
As an unemployed dad with two young kids, I worry about falling into the permanent underclass as AI wealth pulls further ahead. It doesn’t help that I’m living paycheck to paycheck again, thanks to venture capital calls that came in bigger and faster than expected.
So I’ve been combing through every income stream I have, looking for ways to earn more. And one stream stood out: my rental property.
The Temptation To Raise Rents Is Real
San Francisco rents are surging. My tenants are paying about $1,250 a month below what I could likely get today. That’s $15,000 a year, which would cover a meaningful chunk of my next capital call.
And here’s the uncomfortable part. Rich tenants are everywhere in San Francisco right now. When the people renting your house are suddenly worth millions, it’s easy to think: they won’t even notice a few hundred extra dollars a month. Meanwhile, I’d notice it every single month given I’m cash strapped at 49.
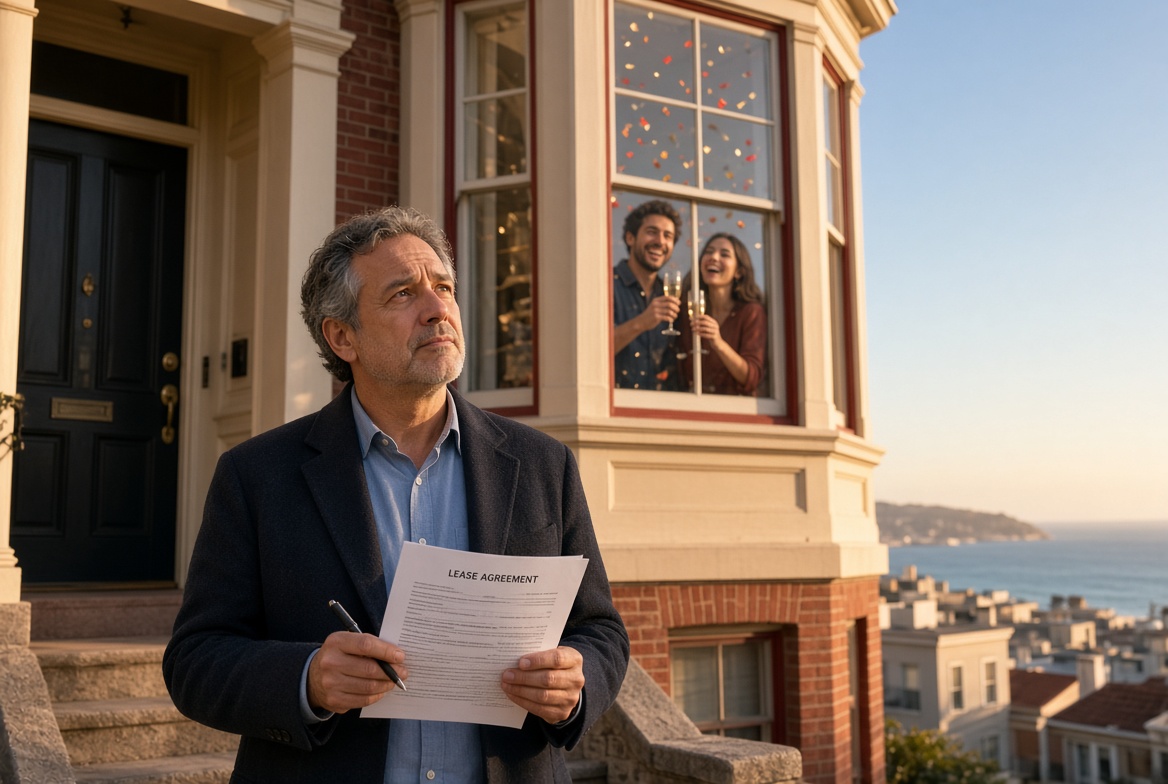
So naturally, I got to wondering. If your tenants suddenly strike it rich, does that change what they owe you? At the very least, should they at least pay market rent?
Plenty of landlords would say yes. Being a landlord is a business, not a charity. If the market is hot and tenants can afford it, why not charge market rent? The answer is not as simple as I initially thought.
Boom Times In San Francisco Housing
After a down period in 2022 and 2023, the San Francisco housing market has gone parabolic thanks to the AI boom. I
San Francisco now has the strongest housing market in the country. Citywide rents are up about 27% year over year, with one-bedrooms up 25.4% and two-bedrooms up 26.8% all according to Zumper. This is the latest rent growth of the 100 largest U.S. cities.
Home prices are on fire too. The median San Francisco home sold for about $1.69 million in September, up 14.7% year over year, the fastest growth of any major market. For single-family houses, the median is up about 24%, with 86% selling over asking.
So any San Francisco landlord who signed a lease in 2025 or earlier is likely no longer charging market rent. Not even close.
Created A Schedule Of Rents In The Lease
I’ve been a San Francisco landlord since 2005, when I rented out the first property I bought in 2003. Over the years, I’ve developed harmonious relationships with my tenants thanks to a lease that sets expectations clearly.
One of those expectations is a schedule of rents for the next three years in the lease so both tenants and landlord can budget. The increases are capped at 3% a year. The schedule is intended to provide clarity and rewards tenants for following the lease. If tenants are in good standing, I follow the schedule each year. If not, I’m free to raise the rent within the law with proper written notice.
Every prospective tenant has appreciated this clarity. And even though a landlord usually leaves money on the table by raising rent below market, the peace that results is usually worth more than the extra dollars.
When it comes to owning physical real estate as part of your retirement portfolio, the biggest battle is having the patience to hold for as long as possible. Owning rental property is a war of attrition, and my faith in humanity has been tested a couple times as a landlord.
Falling Behind Big Time On Market Rent
In July 2025, my tenants of 1.2 years gave notice. That was disappointing because I thought they’d stay at least three years. In fact, 2025 was a turbulent year with three tenant turnovers. That’s life as a landlord. You either sell or find new tenants, and I’ve learned a few tricks on how to minimize vacancy.
For this property, the previous tenants were paying $8,995 a month. I decided to test the market at $9,995. In three weeks, I found great tenants, a couple who wanted the entire five-bedroom, four-bathroom house to themselves. Two home offices, a gym, and ocean views were on their wish list. Yes, all types of people spend six figures a year on rent.
Since then, the rental market has gone ballistic. I could most likely rent the house for $11,000 to $12,000 a month today. Let’s call it $11,500, which is conservative given citywide rents are supposedly up about 20-25%. But when the one-year anniversary came on October 1, 2026, the rent only went up to $10,250, a 2.5% increase. True to the lease, I followed the schedule because the tenants were in good standing.
The cost of following the schedule is about $1,250 a month, or $15,000 a year. And the longer the tenants stay, the bigger the opportunity cost. So think twice before writing a fixed rent schedule for new tenants. Instead of three years, consider two. And instead of a fixed 2.5% increase, consider a range of 2% to 8% for more flexibility.
There Is No Cap On Landlord Costs
Rent control is great for tenants who benefit from it. But for landlords, there’s no such thing as cost control. Insurance, maintenance, and labor costs are all rising faster than inflation.
If a landlord doesn’t charge market rent, profit margins get squeezed. Mismanage the rent schedule long enough and the profits disappear, which is why some landlords pull their properties off the market altogether. See what’s happening NYC.
My initial thinking was that I was testing the market in 2025, and I was satisfied with the result. As long as rent rises 2.5% a year, I should at least cover 80% of the rising cost of insurance and basic maintenance.
My tenants are also relatively young with plenty of options on their side. I don’t expect them to stay longer than five years. More realistically, three. With so much wealth coming their way, I would think they’d want to buy a property eventually.
Remember, I expected my previous tenants to stay three years, and they left after 1.2 despite having a daughter in school.
So at the end of the day, I’m following the lease I drew up and signed. If my tenants are still there after their fourth year, I’ll reconsider whether to raise the rent to market.
Your Tenant’s Financial Windfall Is Separate
Back to the original question. Should a tenant’s sudden wealth change anything?
Tenants strike it rich all the time. One buys a lottery ticket on a whim and hits for $20 million. Another’s startup gets acquired by Big Tech. Another inherits a fortune from a grandparent they visited twice. Another gets promoted to managing director and starts earning well over $1 million a year overnight.
Now flip it around. Tenants also get laid off, go through divorces, get sick, and watch their portfolios drop 40%. How many landlords voluntarily cut the rent when that happens? Not many.
You can’t have it both ways. If a tenant’s bad luck doesn’t lower the rent, their good luck shouldn’t raise it.
A lease is a promise about a house, not a royalty on your tenant’s life. If my tenants make $50,000 or $50 million this year, the rent schedule stays the same. That’s the whole point of putting it in writing.
There’s also a practical side. Tenants who come into money are more likely to buy a home than renew. Pressure them and you may only speed up their exit. One vacant month at $10,250 wipes out roughly eight months of my $1,250 discount.
When good tenants eventually leave, I’ll reset to market rent. Until then, my word is worth more than $15,000 a year.
It’s Hard To Raise The Rent As A Mom & Pop Landlord
My problem as a landlord is that I optimize for peace and harmony. A property manager would likely optimize for maximum profit plus harmony. But I’m not about to give up 1 to 2 months of rent a year when I don’t have a day job and have been managing properties since 2005.
Despite my experience, I still find raising the rent deeply uncomfortable. I’ve written about how to raise the rent and extend a lease and even how to raise rent without guilt. Clearly, I’m still a work in progress.
That discomfort is the main reason I hand over a three-year rent schedule up front to avoid any future awkwardness. When a new tenant’s enthusiasm is highest, they see the terms. If they agree, they sign with no surprises. If not, no big deal.
Honoring The Lease Is The Way To Go
Even though the lease goes month-to-month after the first year and the schedule isn’t legally binding, honoring my word has paid off over 21+ years. Changing the terms on tenants after a year is not the path to harmony, even if it is my right to do so.
If your tenants have caused no disturbances, always paid on time, been honest about what they’ve broken, and paid to fix it, it’s simply not worth raising the rent to market if you’re still cash flow positive. Again, the greatest wealth-building opportunity is holding your property for as long as possible. More harmony means longer hold periods.
Also, when a company pays a dividend, its share price drops by the amount paid out. When a house pays you rent every month, its value doesn’t drop by a commensurate amount. Wear and tear is real, but it’s nothing like a dollar-for-dollar decline. Rental property income is superior to dividend stock income in this way.
So I’ll follow my three-year rent schedule and wait until October 2029 to revisit market rent if they are still around. Honoring the lease isn’t charity. It’s how you keep good tenants and protect your reputation as a landlord, which pays off for decades.
A Word To Tenants
If rents are surging in your city, follow the lease and give your landlord zero excuses to raise the rent. To improve your odds further, send a small gift from time to time. Even a $25 gift goes a long way. It may sound ridiculous, but this kind of emotional intelligence can save you thousands of dollars.
Also, the more self-sufficient you are at fixing things and the less you contact your landlord, the more likely your rent stays reasonable. Besides, who wants to go back and forth with a landlord anyway?
Just know this leeway mostly exists with mom-and-pop landlords. A corporate landlord’s pricing software doesn’t care about your gift. A human landlord with a conscience might.
Readers, if your tenants suddenly struck it rich from an IPO, inheritance, or lottery win, would you raise the rent to market or honor your original terms? Should landlords cut the rent when tenants fall on hard times, if they’d raise it when tenants get rich? Do multi-year rent schedules make sense, or are they just leaving money on the table? And tenants, would you send your landlord a $25 gift to keep your rent down, or would that feel like a bribe?
Invest In Real Estate Without The Tenant Drama
If this post made you realize being a landlord means leaving money on the table, eating rising costs, and agonizing over rent increases, there’s another way to own real estate.
Check out Fundrise, my favorite private real estate investing platform. Instead of fixing toilets or negotiating leases, you can invest in a diversified portfolio of residential and industrial real estate, starting with as little as $10.
No midnight calls about leaky faucets or awkward rent conversations. No tenants striking it rich while you honor a three-year rent schedule. 100% passive instead.
I’ve personally invested with Fundrise, and they’ve been a long-time sponsor of Financial Samurai.